Data Advisory / Funding Decisions / October 2026
AI Data Licensing vs. Debt and Equity: A Funding Decision for Business Owners
How licensing eligible business records can reduce a funding gap, with an assessment of the commercial conditions that determine whether it belongs in the plan.
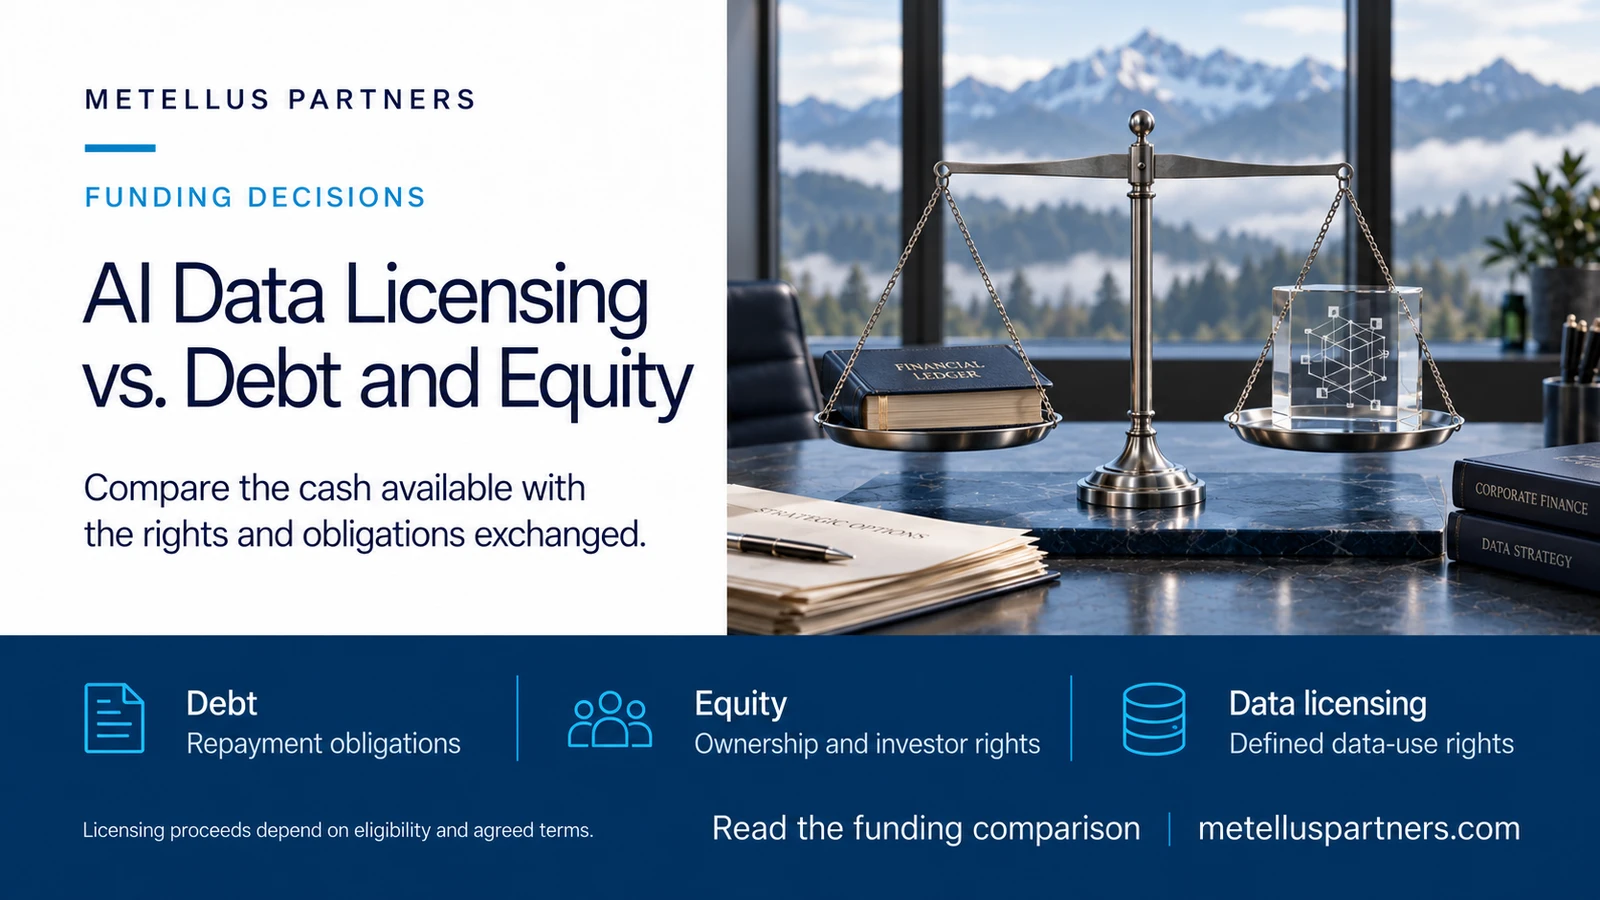
A funding decision begins with the remaining cash requirement
A completed data-licensing transaction can reduce the amount a company needs to borrow or raise from shareholders. The commercial question is whether the proceeds arrive when needed, remain available for the intended purpose and justify the rights granted.
That gives AI data licensing a place in a funding discussion. It creates a possible source of cash from business records, alongside the established choices of debt and equity.
The distinction matters: licensing is a commercial transaction involving permission to use defined material. Its proceeds can help fund a business, but an expression of buyer interest is not committed financing.
Metellus Partners’ view is that owners should evaluate eligible records early enough to assess the opportunity while retaining other funding options. A cash deadline should be supported by funds whose availability is understood.
The commercial market exists; the outcome is company-specific
Mercor publicly offers to license enterprise workflow data and compensate participating businesses. Its program describes payment after delivery of the anonymized dataset to the buyer. Scrimdata describes a scoped license for an anonymized derivative of company history, with permitted uses governed by agreement. Mercor · Scrimdata
Those offerings establish an avenue for assessment. They do not establish the value of any particular company’s records, the likelihood of an offer or a standard closing timetable.
Before including licensing proceeds in a funding plan, establish which records interest the buyer, what permissions are available and which conditions must be satisfied before payment.
For an introduction to the underlying market, see our article on the commercial opportunity in company records.
Compare what the business gives in exchange
Conventional debt involves repayment of borrowed principal and interest under agreed terms. An equity raise brings in capital in exchange for an ownership stake. ICAEW explains these basic distinctions; individual instruments can combine features of both. ICAEW’s finance guide
A standalone license paid for entirely in cash need not issue shares or create loan principal. The economic cost instead sits in the rights granted, delivery work, continuing obligations and opportunities the company gives up.
The following comparison is a framework for reviewing proposed terms, rather than a ranking of funding sources.
| Route | What is exchanged | Main commercial question |
|---|---|---|
| Conventional loan | Cash now in exchange for repayment and agreed charges; security or covenants depend on the facility. | Can the business support the repayments and restrictions? |
| Equity investment | Capital in exchange for ownership and negotiated investor rights. | Does the capital and investor contribution justify the ownership and governance terms? |
| Cash-paid data license | Payment for defined data-use rights, subject to delivery and contractual obligations. | Are the net proceeds sufficient for the rights and obligations granted? |
Non-dilutive does not establish the full cost
A license can preserve the existing shareholding structure while restricting future commercial uses of the licensed material. Exclusivity, duration and onward licensing therefore belong in the valuation discussion.
Scrimdata, for example, describes non-exclusive licensing as its default and makes exclusivity a negotiated choice. That is one provider’s stated model; the signed agreement determines the actual rights. Scrimdata’s licensing model
Review whether the company can continue using the records internally, offer overlapping material to another buyer or develop its own data product. A larger payment deserves closer scrutiny if it closes off valuable future options.
Contractual exposure also remains relevant. Delivery commitments, warranties, indemnities and refund provisions can create obligations even where the transaction contains no borrowing.
Our suggested assessment compares the proposed net cash benefit with those restrictions and obligations. The absence of share issuance answers only one part of the decision.
Use net available cash in the funding plan
Begin with the amount the company needs, the date it needs it and the expenditure that money must support.
Then evaluate a licensing proposal using the cash expected to remain after company-borne preparation costs, transaction expenses, applicable taxes and any required reserves or restrictions on use. Confirm the treatment with the company’s finance and legal advisers.
Keep an initial estimate separate from an agreed payment obligation. A signed contract still requires a review of acceptance conditions, delivery milestones, the payer’s ability to pay and collection timing.
Where a licensing payment has been received and is available for the planned expenditure, it reduces the remaining cash requirement by that available amount, all else equal. It does not eliminate a larger funding need.
Cash collection and financial-reporting treatment also require separate consideration. Ask the company’s accountant how the arrangement should be recognized; avoid presenting a single licensing payment as recurring operating performance.
Funding purpose determines where licensing competes
For a defined, one-time expenditure, available licensing proceeds can fund part of the requirement and reduce the amount sought elsewhere. A business retaining its financing options can evaluate that contribution without depending on a speculative transaction.
Recurring working-capital needs require a different assessment. A historical archive and an ongoing credit facility do not provide the same pattern of availability. The British Business Bank describes loans, overdrafts and credit lines as distinct debt products; their agreed terms determine how they can be used. British Business Bank
For a substantial expansion, acquisition or prolonged investment program, compare the scale and timing of the whole requirement. A licensing receipt can be useful while leaving a need for financing with a longer duration or greater capacity.
Equity also deserves assessment beyond the amount raised. A proposed investor’s contribution, ownership rights and role in the business are different considerations from a data buyer’s permission to use a dataset.
The most credible competition is at the level of the remaining funding gap: a licensing transaction can change how much external funding is required, even when it cannot replace the broader capital plan.
Rights and confidentiality determine whether the opportunity is usable
Before granting access, identify the records proposed for licensing and ask the company’s advisers to review ownership, customer obligations and any existing financing or commercial agreements affecting the proposed transaction.
Anonymization requires its own assessment. The UK Information Commissioner’s Office distinguishes anonymous information from pseudonymized data that can still be connected to a person. It also states that anonymizing personal data is itself processing. Its guidance is UK-specific and marked as under review. ICO guidance
A provider’s description of its process does not establish that a particular company has permission to supply the proposed records. The review needs to address the actual material, applicable requirements and agreed handling arrangements.
Start with a description of the archive. Technical access, samples and transfers should follow an approved scope and appropriate review.
Assess the opportunity before making it part of the financing assumption
An owner-ready assessment should explain the business processes represented in the records, the period covered, the rights available and any categories excluded from consideration.
Connect that assessment to the funding objective: required amount, payment deadline, alternative sources and the consequence of a delayed or unsuccessful licensing discussion.
Proceed on commercial terms that justify the transaction in their own right. A licensing estimate should not become the reason a company abandons a necessary financing process.
Explore a data-licensing introduction through Metellus Partners
For owners and executives of companies with 20+ employees, Metellus Partners offers an initial conversation about whether business records warrant a specialist licensing assessment.
Describe your company, the systems holding its operating history and the funding objective you are evaluating. Leave confidential files and credentials out of the initial enquiry.
Through our Data Advisory service, the first step is to establish fit and discuss an introduction. Dataset acceptance, payment and transaction terms remain subject to specialist review and agreement.
Sources and references
Insights
Perspectives for the next decision.
Explore Metellus briefings on demand generation, commercial operations and data licensing.
3 briefings
Data Advisory
Your Company Does Not Need to Be a Tech Business to License Data for AI
Six assumptions to reconsider before dismissing the commercial potential of your company’s operating history.
Data Advisory
AI Data Licensing: The Commercial Opportunity in Company Records
What leaders of companies with 20+ employees should understand about licensing business records for AI development.
Revenue Advisory
2027 Commercial Finance Origination Report
U.S. outlook and operating priorities for qualified pipeline development. Research cutoff: September 21, 2026.